Categories more
- Adventures (213)
- Arts / Collectibles (374)
- Automotive (888)
- Aviation (383)
- Bath, Body & Health (3913)
- Children (138)
- Cigars / Spirits (295)
- Cuisine (727)
- Design / Architecture (1122)
- Electronics (244)
- Entertainment (163)
- Event Planning (295)
- Fashion (555)
- Finance (207)
- Gifts / Misc (141)
- Home Decor (589)
- Jewelry (416)
- Pets (92)
- Philanthropy (124)
- Real Estate (401)
- Services (225)
- Sports / Golf (216)
- Vacation / Travel (1074)
- Watches / Pens (237)
- Wines / Vines (872)
- Yachting / Boating (9084)


The "Storm Chaser" Problem: A Homeowner's Guide to Checking Repair Bids

Published
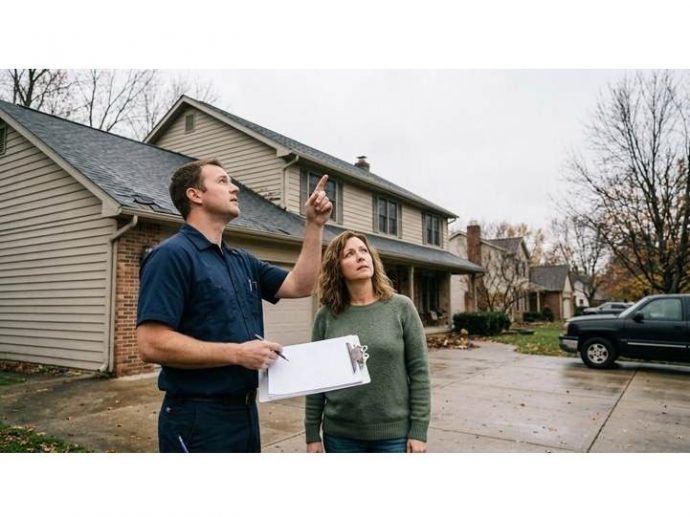
11/03/2026 by By a storm restoration industry contributor.After a big storm, your first goal is to get your home safe and fixed. A knock on the door from a contractor can feel like a relief. But the first person to show up isn't always the best choice. Out-of-town "storm chasers" often follow bad weather. They move from town to town, do fast, poor-quality repairs, and then disappear. This can leave you with a warranty that no longer works and problems that aren't fixed.
The key is to tell the good local contractors from these crews that just pass through. Finding a list of contractors is easy. A quick online search for storm damage repair contractors near me will give you options. The hard part is knowing how to check them out when you're stressed. You need a clear plan to make a good choice when you feel rushed and a lot is on the line. This guide gives you that plan.
Quick answer: The best way to avoid bad contractors is to have a clear way to check them. Focus on checking a company's local street address, their contractor license, and their insurance. A good contractor gives you a detailed, written estimate and knows how to work with insurance companies.
What's inside
- What's the difference between a local contractor and a "storm chaser"?
- How can I verify a contractor's license and insurance?
- What should a legitimate repair estimate include?
- How do good contractors handle insurance claims?
- What are the most common red flags to watch for?
- Frequently Asked Questions About Storm Repair
What's the difference between a local contractor and a "storm chaser"?
The main difference is that local contractors are accountable. This means they are responsible for their work. A local contractor has a real business and a reputation to protect in your town. A storm chaser is just in town for a short time and often disappears after the job is done. Understanding this difference is key to protecting your home and your money after a storm.
Storm chasers are companies that move around, following bad weather across the country. They show up in a neighborhood right after a storm and use pushy sales tactics at your door. Their goal is to do a lot of jobs quickly. They try to sign as many homeowners as they can, do fast and poor-quality repairs with cheap materials, and then leave for the next town before anyone finds the problems.
A local, long-term contractor works differently. Their business is built on good reviews and a strong reputation. They have a real office, know local suppliers, and understand local building rules and weather. Because they are part of your community, they are responsible for their work. If a problem comes up a year from now, you know where to find them.
"Ask any potential contractor for a list of three local projects they completed over a year ago. Then, go look at them. An out-of-town crew won't have a local history, but a good company will be proud to show you their long-term work. This simple step filters out most crews that are just passing through."
The problems from a bad repair job cost more than just the first bill. A poorly installed roof can cause slow leaks. This can lead to hidden water damage, mold, and a weaker house structure. For example, a homeowner might hire a fast-talking crew for a cheap hail damage repair. They replace the shingles but reuse old flashing around the chimney. Months later, a slow leak ruins the attic insulation and ceiling drywall, costing thousands to fix.
Also, your insurance company might deny future claims if they find the damage was caused by a bad repair job. The money you think you're saving on a cheap offer is often spent two or three times over fixing the new problems.
How can I verify a contractor's license and insurance?
You can check if a contractor is legitimate by asking for their license number and proof of insurance. Then, you must check this information for yourself with the groups that issued them. Never just take the contractor's word for it or trust a paper they hand you. Checking these details is your best protection against scams and legal problems.
A real contractor will be happy to give you their general contractor license number. Licensing rules are different from state to state and city to city, but they all have the same goal: to make sure the contractor has basic skills and is responsible to an official group. You can usually check the license number on your state or city's official website. If a contractor doesn't want to give you their number or says they don't need one, that's a big red flag.
When you look up their license, check for more than just an "active" status. The licensing board's website often lists public complaints or disciplinary actions. This gives you a better look at their professional history. A clean record is a very good sign.
Their insurance is just as important. You need to check for two types of coverage:
- General Liability: This protects your property from damage the contractor might cause. If a worker accidentally starts a fire or breaks your siding, this insurance pays for it. Without it, you might have to sue the contractor to pay for the damages.
- Workers' Compensation: This protects you if a worker gets hurt on your property. Without it, you could be responsible for their medical bills and lost pay. An injury at your home could lead to a very expensive lawsuit.
"Don't just accept a copy of an insurance paper from the contractor. Ask for a Certificate of Insurance (COI) to be sent to you right from their insurance agent. This proves the policy is active and real. The certificate will list the company's name, policy number, and coverage amounts. Make sure the company name on the policy is the same as the name on your contract."
If a contractor refuses to give you these documents or pressures you to sign before you can check them, walk away. A professional company expects you to do this kind of careful checking.
What should a legitimate repair estimate include?
A proper estimate is a detailed list that shows all materials, labor, and steps, not just a final price. This detail is a must-have. It becomes part of your contract and protects you from surprise costs and arguments later. A vague estimate is a major red flag.
A professional bid is a line-item estimate. This means every part of the job is listed separately with its own cost. This transparency allows you to see exactly what you are paying for. It also helps you compare different bids fairly.
Your estimate should clearly break down the following items:
- Materials: Specific product names, brands, colors, and quantities. For a roof, this includes the type of shingles, underlayment, and flashing.
- Labor: The cost for the work, including how many workers and the expected time.
- Debris Removal: The cost for dumpsters and hauling away old materials.
- Permit Fees: Any costs for pulling required local building permits.
- Payment Schedule: A clear plan for when payments are due. Never pay for the whole job upfront.
- Warranty: Details on both the material warranty from the manufacturer and the workmanship warranty from the contractor.
"A vague estimate is a blank check you are handing to the contractor. If a line item just says "Roof Repair: $8,000," you have no control. A detailed line like "Replace 25 wind-damaged GAF Timberline shingles" protects you and sets clear expectations."
How do good contractors handle insurance claims?
A reputable contractor acts as your project manager, not your claims adjuster. They should have experience working with insurance companies. They can provide the detailed documentation your insurer needs to process your claim correctly. However, they should never act as your legal representative.
A good contractor will meet with your insurance adjuster at your property. They can point out damage the adjuster might miss and explain the local building codes that affect the repair. They often use the same estimating software as insurance companies, like Xactimate. This helps make sure their estimate aligns with what the insurance company expects to pay.
Be very careful if a contractor offers to "eat your deductible" or handle the entire claim for you. Waiving a deductible is a form of insurance fraud in many states. Also, be wary of signing an "Assignment of Benefits" form. This document can give the contractor the right to bill your insurance company directly, taking you out of the process entirely.
What are the most common red flags to watch for?
Knowing the warning signs of a storm chaser can save you a lot of trouble. Trust your instincts. If something feels wrong, it probably is.
Here are some of the most common red flags:
- High-Pressure Sales: They insist you must sign a contract immediately. They might say the "special price" is only for today.
- Large Upfront Payment: A contractor who asks for a large down payment or the full amount before work begins is a risk.
A typical down payment is 10 to 30 percent. - Vague Contract: The contract should include all the details from the line-item estimate. If it is blank or has very little detail, do not sign it.
- No Local Address: They use a P.O. box or have no local office you can visit. Check their address online to see if it is a real, physical location.
- Unmarked Vehicles: A professional company will have its name, phone number, and license number on its trucks.
Frequently Asked Questions About Storm Repair
How long does storm damage repair take? The timeline depends entirely on the scope of the work. A simple roof patch or gutter replacement might take only a day. A full roof replacement usually takes two to three days. If your home has major structural damage or flooding, the repair process could take several weeks or even months. Factors like weather, material availability, and local permit approvals can also affect the schedule.
What factors influence the cost of storm damage repair? Several key things determine the final cost. The biggest factor is the extent of the damage. The quality and type of materials you choose also play a large role. For example, architectural shingles cost more than standard 3-tab shingles. Labor rates in your area, the complexity of the job, and the cost of any necessary permits will also be included in the total price.
About the author
This guide is from a contributor at Restoration Contractors LLC, a general contractor in Arvada, Colorado. The company provides property restoration and storm damage repair services.
Comments